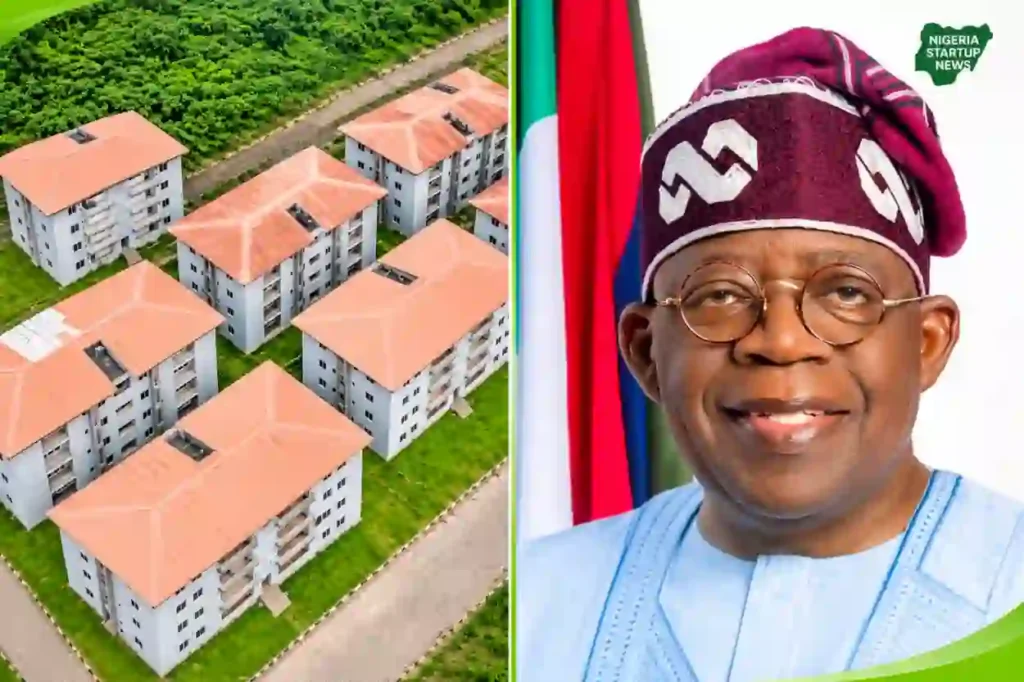
The Federal Government has explained how Nigerians can purchase houses without paying the entire cost upfront through a mortgage facility offering loans of up to ₦100 million.
 Follow us on Google News
President Bola Tinubu said the arrangement, backed by the Ministry of Finance Incorporated (MOFI) Real Estate Investment Fund (MREIF), is designed to make homeownership more accessible to eligible Nigerians.
The facility carries a fixed annual interest rate of 9.75 per cent, with repayment periods of up to 20 years, depending on borrowers’ circumstances.
Under the scheme, prospective homeowners may qualify with an initial contribution starting at 10 per cent of a property’s value, while approved lenders finance the balance.
For example, someone purchasing a ₦10 million house could contribute ₦1 million initially and repay the remaining amount through monthly mortgage instalments.
Tinubu said the estimated monthly repayment for that example would be approximately ₦85,400 over 20 years, although actual repayment terms depend on the lender.
Applicants must be Nigerian citizens aged at least 21, meet income and credit requirements and complete repayment before the applicable age limit.
Both salary earners and eligible self-employed Nigerians may explore the arrangement, but lending institutions will assess their capacity to repay.
The government also said eligible contributors to the Contributory Pension Scheme may use part of their retirement savings towards the required deposit.
The facility is not a grant or free housing scheme. Borrowers must repay their loans, including interest and applicable charges.
How to apply
Interested Nigerians should visit the official MREIF website at https://www.mreif.com.ng/homebuyers or begin pre-qualification at https://housing.mreif.com.ng/pre-qualifier.
Applicants should provide information about their income, employment, age, deposit and preferred repayment period, then identify an eligible property.
Required documents may include identification, payslips, employment records, utility bills, tax documents and property title papers.
They can submit applications through designated channels or participating banks, which will review credit history, property documents and monthly repayment capacity before approval.
Applicants should verify current deposit requirements with their chosen bank and avoid anyone demanding unofficial processing payments.